E-Invoicing Wave 25: How to Prepare Your Business for ZATCA Integration in 2027
📅 19/11/2026
E-invoicing Wave 25 targets Saudi businesses according to the VAT-taxable revenue criterion announced by the Zakat, Tax and Customs Authority in July 2026. To prepare for integration with ZATCA, a business needs to verify its official notification, identify all invoice issuance points, and test its technical solution and accounting procedures before its mandatory integration date. Choosing a suitable cloud accounting system can help manage these tasks, but it does not replace testing actual data or relieve the business of its responsibility for compliance.
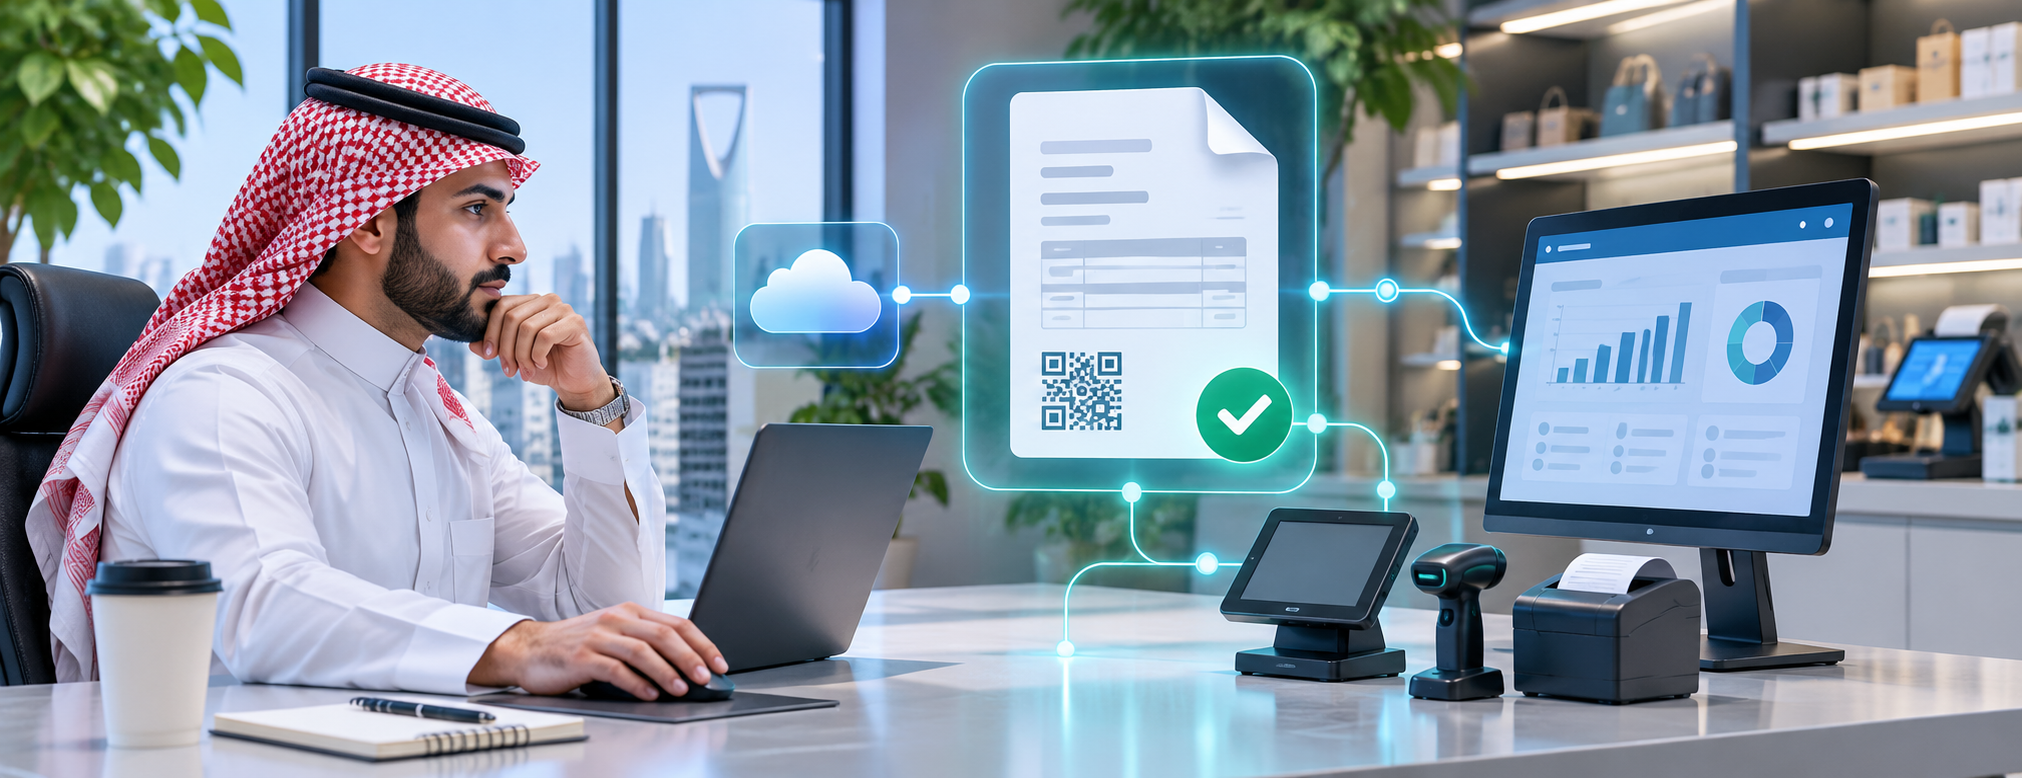
Your business may have been issuing electronic invoices for years, yet additional work is required when entering the integration phase. The difference is not simply adding a quick response (QR) code to an invoice, but moving to structured electronic document exchange with the Fatoora system and monitoring its results. This guide explains a practical preparation plan for a retail store, service establishment, or small company, with hypothetical examples in Saudi riyals.
Who Is Covered by the Twenty-Fifth Group (E-Invoicing Wave 25)?
According to ZATCA’s announcement of the twenty-fifth group, published on 24 July 2026, the selection criterion covers businesses whose VAT-taxable revenues exceeded SAR 187,500 in any of the years 2022, 2023, 2024, or 2025. The Authority announced that it would notify the relevant businesses in preparation for integration beginning on 1 February 2027. Do not assume that the criterion alone determines your business’s deadline; check its specific notification, as it may already belong to an earlier group.
For example, if taxable revenues amounted to SAR 165,000 in 2022, SAR 210,000 in 2023, SAR 180,000 in 2024, and SAR 150,000 in 2025, the revenue in 2023 exceeds the stated threshold. A decline in revenue in the latest year does not negate the fact that the criterion was met in a previous year. A business that reached exactly SAR 187,500 in one year and did not exceed it in any other year cannot be considered to have exceeded the threshold based on that figure alone.
Do not confuse the group selection threshold with the VAT registration threshold. The former is a criterion for scheduling integration, not an automatic change to registration obligations. Nor should you rely on total bank deposits to determine taxable revenue: deposits may include loans, internal transfers, or amounts relating to different periods. Start with tax returns and tax records, and seek specialist advice if you have exempt transactions or supplies subject to different treatment.
| Year | Hypothetical taxable revenue | Threshold exceeded? |
|---|---|---|
| 2022 | SAR 165,000 | No |
| 2023 | SAR 210,000 | Yes |
| 2024 | SAR 180,000 | No |
| 2025 | SAR 150,000 | No |
What Is the Difference Between Issuance and Storage and Integration with the Fatoora Platform?
The first phase concerns issuing and storing documents electronically in accordance with the requirements, while the second phase adds connectivity with the Authority’s system and the necessary technical and security specifications. The e-invoicing educational materials explain the difference between the two invoice types and the procedures taxpayers need to follow. Having software that prints a well-formatted invoice does not establish that its files meet Phase Two requirements.
Simplified tax invoices are common in businesses selling to consumers, while tax invoices are generally used in business-to-business transactions. In the integration phase, tax invoices follow a clearance process before being shared with the customer, whereas simplified invoices are reported within 24 hours in accordance with the Authority’s rules. The appropriate process must be selected according to the transaction type, not an employee’s desire to speed up printing. Read about the difference between tax invoices and simplified tax invoices to understand situations in which the required fields may differ.
If you operate a store that sells to individuals and issues credit invoices to companies, testing simplified invoices alone is insufficient. Test a cash sale, a sale to a company, a partial return, a discount, and a rejection or connectivity failure. Verify that each document follows the appropriate process without recording revenue twice.
Book a demo to discuss your business’s integration readiness.
Identify All Invoice Issuance Points Before Integration Begins
Start by mapping every place where invoices originate: POS terminals, the credit sales screen, the online store, the sales representative’s app, and branches using an independent system. Counting computers alone is insufficient; multiple users may work on a single issuance unit, and a branch may use more than one technical solution. Ask the solution provider to explain how issuance units are identified and configured according to the actual system architecture.
For each channel, record the responsible person, invoice type, method of accessing the data, and source of the reference number. If sales are entered through an online store and the accountant subsequently issues another invoice from the accounting software, determine whether the first document is an already issued tax invoice or merely an order confirmation. A process must be in place to prevent two independent tax documents from being issued for the same supply without justification.
| Channel | Required test | Evidence of success |
|---|---|---|
| Branch POS | Simplified sale and credit note | Linked document and reporting status |
| Business sales | Tax invoice | Clearance result before sharing |
| Online store | One order and one invoice | Order number linked to document |
| Additional branch | Issuance unit configuration | Unit identification and transaction log |
Multi-branch accounting management helps explain how the distribution of operations affects controls. Maintain a separate record for each channel identifying who reviews its results and who is authorized to stop issuance when a significant error is discovered.

Review Business, Customer, and Product Data
Start with the data repeated across thousands of invoices. Verify the supplier’s name, tax identification number, address, and the information required for each invoice type. Review business customer details instead of relying on an old record containing an incorrect tax number. The guide to verifying tax identification numbers can help when reviewing the parties’ information.
For products, do not assign a default tax rate to all items without reviewing them. Tax treatment may differ according to the nature of the supply. Assign each item to the correct category, specify whether the price includes tax, and ensure that discounts are correctly allocated across line items. If the business provides a service and a product in a single offer, review how each component is presented according to the nature of the transaction.
For example, a product priced at SAR 115 including 15% VAT has a pre-tax value of SAR 100 and VAT of SAR 15. If an employee enters SAR 115 as the tax-exclusive amount, however, the total becomes SAR 132.25. The technical calculation may be correct, but the invoice does not reflect the agreed price. Therefore, test prices before linking them to customer data.
How Do You Test a Cloud Accounting System in Preparation for ZATCA Integration in 2027?
Ask the provider for a practical demonstration using test data rather than real customer data. Review how electronic invoices are generated in the required format, how submission statuses are managed, how documents and responses are stored, and how related notes are issued. Do not settle for viewing the printed invoice screen. Review the e-invoicing software page to identify the functions you want the team to explain, then compare them with the Authority’s requirements and your subscription package.
Create a test set containing ordinary invoices and exceptional cases. If you have a tax invoice for SAR 1,150, ask to see its status before and after clearance, then verify that the customer’s account has been debited for the correct amount and that output VAT is SAR 150. Next, process a return of SAR 230 through the appropriate credit note procedure. The accounting results should match the documents; successful integration alone is not sufficient.
Also verify that issued documents cannot be tampered with and that clear permissions and an audit trail are available. A provider’s inclusion in the Authority’s indicative list does not constitute blanket approval of every solution or configuration; responsibility remains with the taxpayer. Review the solution providers directory and disclaimer before making a contracting decision.
Explore subscription options and ask about the scope of integration and support.
A Preparation Timeline from November to February
The remaining period can be divided into measurable stages, brought forward or postponed according to the notification date and the size of the business. Do not wait until the final day to test submission. In November, identify the responsible people and verify the wave and data sources. In December, clean the data and test operations. In January, conduct a full operational trial and review exceptions. Before the mandatory deadline, verify production environment configuration and support procedures.
| Proposed period | Task | Reviewable deliverable |
|---|---|---|
| November 2026 | Identify channels and data | List of issuance units and responsibilities |
| December 2026 | Invoice and tax testing | Log of successful and failed cases |
| January 2027 | Configuration, training, and reconciliation | Acceptance and go-live record |
| Before the specified deadline | Final review and support plan | Clear escalation procedures |
If the provider is delayed in resolving an issue, determine whether it prevents issuance of a tax invoice or relates to a nonessential internal report. Prioritize issues that affect compliance and document accuracy. Do not treat the project schedule as an extension of the statutory deadline; contact the Authority through its official channels when necessary.
Reconcile Invoices and Accounting Entries After Configuration
The accountant needs to reconcile document counts and values, not simply check that the submission screen is free of alerts. Separate tax invoices from simplified invoices, credit notes from debit notes, and cleared or reported documents from cases awaiting processing. Then compare net sales and tax with accounting reports. The guide to the accounting system workflow explains the relationship between recording transactions and reporting.
Suppose a branch issues 120 simplified invoices in one day, with a total value of SAR 13,800, all subject to the standard rate. Net sales are SAR 12,000 and VAT is SAR 1,800. If the reporting log shows only 118 invoices, do not conclude that the difference is SAR 230 merely by dividing the total by the number of invoices; retrieve the identifiers, actual values, and statuses of the two remaining documents. One may be a return or an invoice of a different value.
Maintain a daily list of invoices requiring follow-up, recording the issuance time, response, and latest action. Do not resolve a submission error with an accounting entry that automatically reverses revenue; the goods may already have been delivered to the customer. Correcting the tax document requires following the procedure appropriate to its status, while the accounts reflect the actual economic event.
Start a system trial and test the sales cycle and reports using hypothetical data.
What Should You Do If You Have Multiple Branches or Sales Channels?
First, establish the legal and tax relationship between branches. Several outlets may belong to a single taxpayer, or they may be independent companies with their own details. Do not copy one branch’s settings to another without confirming the correct tax identity and issuance units. Link each transaction to a cost center or branch when necessary, but do not use a cost center as a substitute for required invoice information.
Consider a company with two branches and an online store: the first branch may issue 80 invoices, the second 50, and the store 30. A total of 160 documents does not mean that there are 160 reporting transactions from one issuance unit. Review each channel’s report, then the consolidated report. If a branch shows zero in the report, check whether it actually made no sales or whether its data failed to arrive. Integration of sales, inventory, and accounting helps explain this relationship, subject to verifying the integration capabilities of the solution in use.

How Do You Train Employees to Handle Exceptional Cases?
Train POS employees to distinguish between a pending order and an issued invoice, and to escalate a rejection to a supervisor. Train accountants to read clearance and reporting results and distinguish customer data errors from technical file errors. Branch managers need to know whom to contact when service is interrupted. Do not grant everyone permission to modify invoicing settings simply to speed up work.
Base training on scenarios: a business customer requests an invoice after a simplified document has been issued, a customer returns part of an order, an online store order is duplicated, or an invoice has no final result. For each scenario, document the permitted action and authorized party. Refer to internal accounting controls when assigning responsibilities, and ask the provider to explain the limitations of offline operation rather than assuming that every system supports every case.
Book a session with the system team to test exceptional cases.
Integration Acceptance Checklist Before Go-Live
Approve go-live when each test has retained evidence and an assigned reviewer. Do not use the phrase “ready for integration” without specifying what has been tested. The acceptance record should include the taxpayer’s identity and issuance units, the type of each document, test results, resulting accounting entries, and open issues with a remediation plan. Retain a copy of the official notification and the verification date.
Also review procedures for storing files and responses, accessing them during a review, and handling connectivity interruptions. Ask the team to confirm that accounting system reports allow sufficient data to be extracted for invoice and tax reconciliation, and that the responsible person can monitor incomplete cases without relying on a WhatsApp message from a single employee.
Practical Scenarios and Advanced Reviews
How Do You Handle Businesses Whose Details Changed Before the Wave Deadline?
An establishment may have become a company, changed ownership, opened branches, or changed its tax registration during the years covered by the group criterion. In such a case, it is not sufficient to transfer the revenue from the old registration to the new one and determine the deadline yourself. Identify the taxpayer to whom the notification relates, the date of the change, and the relationship between the entities, and consult the Authority if anything is unclear. Retain evidence of current registration status and any previous notifications, because the mandatory integration date may relate to circumstances different from the date business activity began.
If the business has moved from old software to a new system, retain the previous documents and their data without reissuing them in the new system merely to complete the archive. Separate the data migration project from the integration configuration project. The business must continue issuing new documents in accordance with the requirements and be able to retrieve earlier records during a review. Ask the provider to specify what will be migrated as reference data, what will remain in a separate archive, and how each can be accessed after the previous subscription ends.
Review Contracts with the System Provider Before Signing
A cloud accounting system provider may offer a subscription covering sales and accounting, but some configuration, support, or additional device integration services may be separate. Request a quotation specifying the number of entities, branches, and issuance units, as well as configuration costs, updates, support, and data retrieval procedures. Do not assume that the phrase “ZATCA-compliant” means that the provider will handle all registration or tax review procedures on your behalf.
Separate responsibilities in the contract: who provides the business data, who configures the solution, who tests invoices, who reviews tax, and who follows up on failures. If the business works with an external accountant, define the scope of their access to reports without granting them technical credentials. If a third party manages the online store, specify who will correct order transfer errors. This division makes it possible to identify the escalation point when a problem arises instead of having responsibility passed between parties.
A Practical Acceptance Test for a Service Business and a Retail Store
In a service business, test a contract with a commercial customer for SAR 5,000 before tax, an advance payment, a final invoice, and a related correction if needed. Successful document generation alone is not sufficient; review how the payment appears in the accounts and how the system prevents tax or revenue from being counted twice on the same consideration. Determine the timing of supply and issuance according to the nature of the contract, then ask the accountant to review the result.
In a retail store, test a SAR 230 transaction paid using two payment methods, followed by a partial return of SAR 115. The effect of the return should be reflected in the document, tax, inventory, and collections as applicable. Also test a sale containing two items in different tax categories if the business includes them. Do not rely on testing a single standard-rated item if the product database is more complex.
| Test | What to record in the acceptance record |
|---|---|
| Business invoice | Document type, clearance result, reference number, receivables impact |
| Advance payment | Required document, tax timing, unearned balance |
| Retail sale | Reporting result, payment details, inventory movement |
| Partial return | Original document reference, reduction amount, tax and refund impact |
| Connectivity interruption | Downtime, document status, recovery procedure |
Organizing the First Week After Integration Begins
Set aside time each day to review the invoice log during the first week. At the start of the day, check the status of issuance units; midway through the day, review cases requiring follow-up; and at the end of the day, reconcile the sales and tax report with the documents. Do not wait until the tax return to discover a problem that began on day one. If invoice volumes are high, focus on exceptions and material amounts while reviewing samples of valid documents.
Define criteria for closing an issue: not merely the disappearance of an error message, but a clear final status, a retained document, a matching accounting entry, and no duplication. If the fix involves a shared setting, retest new invoices after the change. If an issue affects compliance, do not rely on undocumented expectations from the support team; use the Authority’s official channels when necessary. This turns the transition into a project that can be monitored, rather than a technical event that ends as soon as integration is activated.
Ready to Try the System?
Start your free trial or speak with the sales team to help choose the right solution.
Verify Business Readiness Before Moving to the Production Environment
Do not confuse a successful test in a dedicated environment with readiness for actual operation. Before integration begins, review the production environment settings and configured issuance units with the provider, then carry out acceptance procedures in accordance with the instructions. The responsible person must know how to distinguish test data from real data so that training transactions do not enter the business’s reports. For the first actual transaction, verify the document type, response, accounting entry, and tax, then retain the evidence in the project file. If an unexpected situation arises, follow the approved support process and do not generate additional test invoices for real transactions. You can also review accounting and point-of-sale solutions when assessing the scope of financial operations associated with integration.
Frequently Asked Questions
Do all businesses exceeding SAR 187,500 begin integration in February 2027?
The announced criterion relates to the twenty-fifth group, but the business’s notification and previous status with the Authority must be verified. The announcement does not postpone the deadline of a business already obligated under an earlier group.
Is a QR code on the invoice sufficient?
No. The code is one element of the document, while Phase Two includes structural and security requirements as well as clearance and reporting procedures.
Do I need to purchase a new POS terminal?
Not necessarily. This depends on whether the solution, technical infrastructure, and existing devices meet the requirements. Test the solution before purchasing devices.
Can I change system providers before the deadline?
This can be considered, but you must plan for record retention, configuration of the new solution, prevention of duplicate invoices, and continuity of compliance.
Does a cloud system guarantee that invoices will not be rejected?
No. Data quality, configuration, integration, and operating procedures all have an impact. Monitor responses and resolve errors according to their status.
Where can I check the latest instructions?
Consult your official notification, the Authority’s e-invoicing pages, and its technical guides. Review them again as the mandatory deadline approaches.
Conclusion
Preparing for e-invoicing Wave 25 starts with verifying the scope of the obligation, then identifying issuance channels, cleaning data, and testing invoices, accounting entries, and notes. The objective is not merely to activate an integration button, but to build a process that the accountant can monitor daily. If you are evaluating cloud solutions, start with the comprehensive guide to cloud accounting software, then request a trial suited to your business.
Start evaluating Digital Plus and the options for preparing your business.
Manage Your Business with Greater Flexibility
Try Digital Business for free. Start issuing electronic invoices designed to meet ZATCA requirements in minutes.