The Accounting Cycle: From Recording Transactions to Financial Reports
The Accounting Cycle: From Recording Transactions to Financial Reports
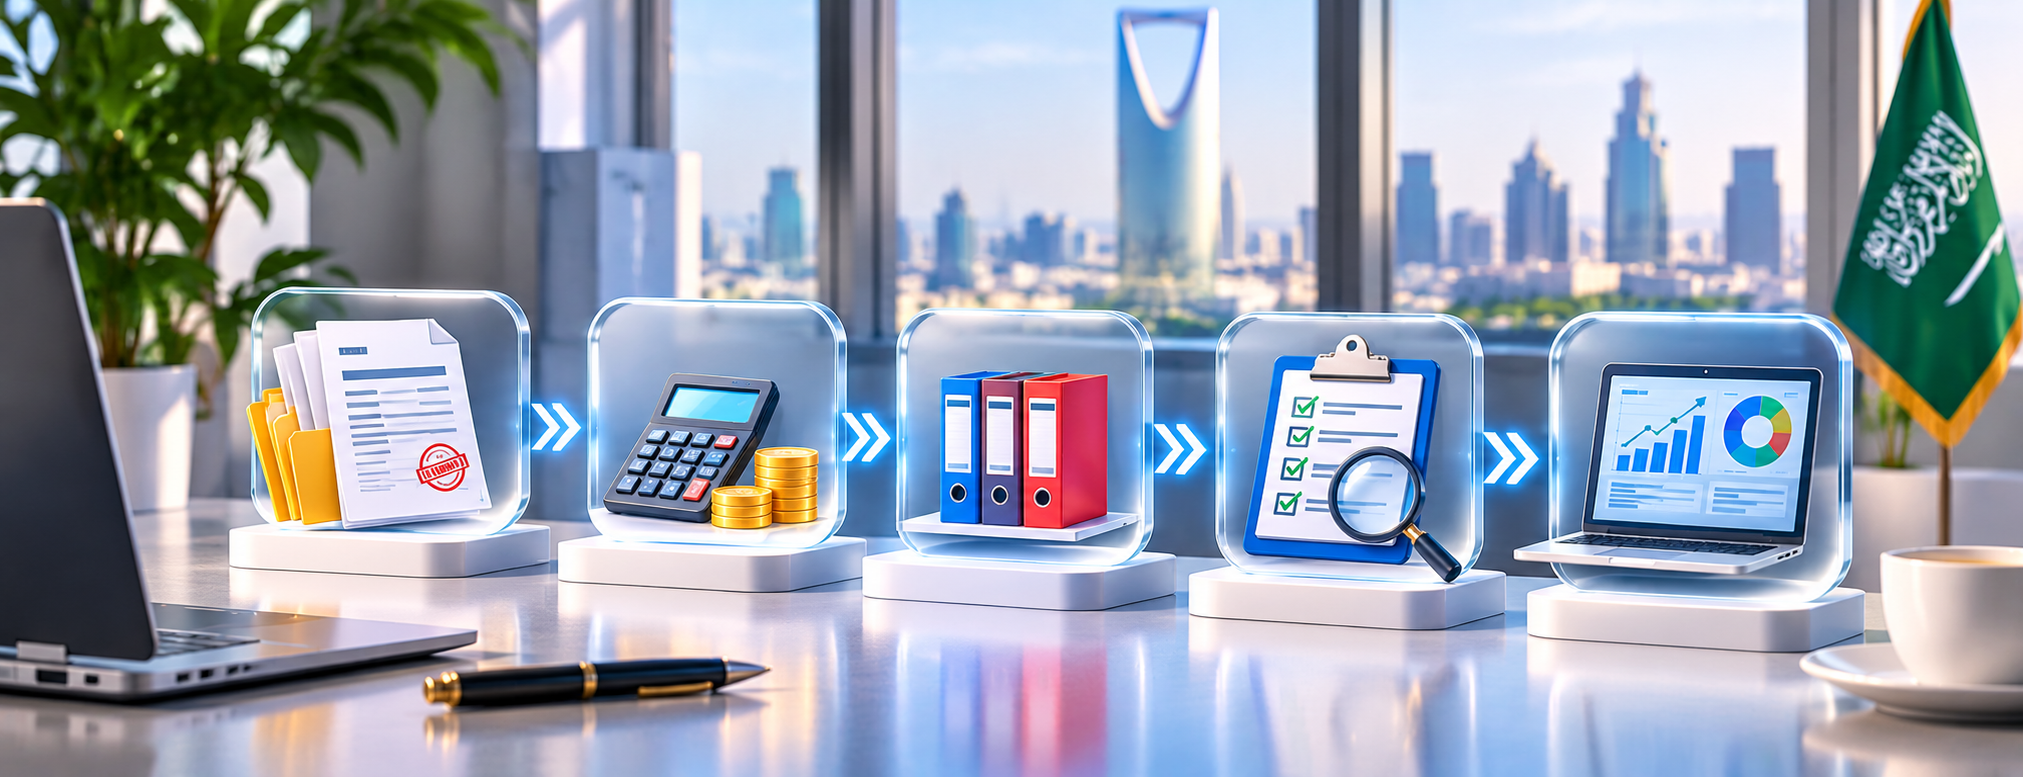
Understanding the accounting-system cycle helps business owners in Saudi Arabia make more informed decisions about organizing and controlling financial transactions. A sound choice begins not with software names or lists of features, but with understanding the procedures the business performs, the documents it relies on, and the reports management needs. This guide provides a practical explanation of the relevant concepts, decisions, and tests, with examples that can be adapted to different business sizes and activities.
When searching for the accounting-system cycle, you may encounter related terms such as the electronic accounting cycle and the stages of the accounting cycle. Similar wording does not necessarily mean identical functions or implementation requirements. We will distinguish the concept, the procedure, and the technology, and explain how to review results rather than relying on broad claims. This information is educational and does not replace advice from a qualified accountant on issues specific to your business, including professional or tax matters.
Source Documents and the Occurrence of Transactions
When examining source documents and transaction occurrence in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. The cycle starts with a document evidencing a sale, purchase, receipt, or payment; its information and validity are checked before entry. Distinguishing the transaction date from the entry date matters when identifying the correct accounting period. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: An invoice received at the beginning of a month for a service relating to the previous month may require treatment under the business’s adopted accrual policy. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
To explore related operational aspects, review accounting and point-of-sale solutions and then verify the actual scope of the functions and how closely they match your business needs.
Account Analysis and Journal Entries
When examining account analysis and journal entries in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. Debit and credit accounts, tax effects, and analytical dimensions are identified before a journal entry is approved. Software may suggest entries automatically, but its configuration still needs testing. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: When part of a credit invoice is collected, the customer’s outstanding balance decreases without recording new revenue if the revenue was already recognized. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
If you are comparing real solutions, you can review the available plans after defining your essential requirements so that the comparison is clear and direct.
Posting to the General Ledger
When examining posting to the general ledger in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. Posting collects journal entries under their respective accounts and makes transactions and balances available for review. Approved entries should not be changed without a documented correction procedure. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: If an expense has been posted to the wrong account, the correction should follow the business’s policy and leave a clear audit trail. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
To explore related operational aspects, review the purchasing management system and then verify the actual scope of the functions and how closely they match your business needs.
Adjustments and Reconciliations
When examining adjustments and reconciliations in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. Reconciliation covers banks, customers, suppliers, inventory, and cash. Differences should be investigated using supporting documents, not cleared with an unexplained aggregate journal entry. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: A bank difference may arise from a card transaction that has not yet settled, rather than an error in revenue; settlement dates should therefore be checked. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
If you are comparing real solutions, you can book a demonstration to discuss your needs after defining your essential requirements so that the comparison is clear and direct.
The Trial Balance and Adjusting Entries
When examining the trial balance and adjusting entries in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. The trial balance helps establish whether debits and credits balance, but it does not guarantee correct classification or complete recording. Accruals, prepayments, and depreciation should be reviewed as appropriate. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: The trial balance can still balance even if a fixed-asset purchase has been recorded as an expense; this shows why analytical review matters. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
To explore related operational aspects, review distribution solutions and then verify the actual scope of the functions and how closely they match your business needs.
Closing the Financial Period
When examining closing the financial period in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. Closing requires completing entries and reconciliations, reviewing late invoices, and locking the period according to authorized permissions. There should be a policy for reopening periods and making corrections. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: A monthly closing checklist can identify the person responsible for each step, its completion date, and the supporting document. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
If you are comparing real solutions, you can compare subscription options after defining your essential requirements so that the comparison is clear and direct.
Preparing and Interpreting Reports
When examining preparing and interpreting reports in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. Financial statements, aging reports, cash-flow reports, and position reports are produced once the period has been set correctly. Comparing them with previous months and budgets helps explain variances. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: An increase in revenue does not necessarily improve liquidity if credit sales or unsold inventory also rise. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
To explore related operational aspects, review the hotel management system and then verify the actual scope of the functions and how closely they match your business needs.
Automation and Exceptions
When examining automation and exceptions in a Saudi business, start by identifying the person responsible for the transaction, the document supporting it, and the result that should appear in the accounts. Automation speeds up recurring entries but requires rules for reviewing unusual transactions, duplicates, and negative balances. Exceptions are among the most important cases to test before launch. The quality of the procedure is measured not only by its speed, but by whether it produces information that can be reviewed and explained, especially when sales, purchases, and payments involve several employees or branches.
Practical example: Test a duplicate invoice, a return after period closing, and an overpayment to see how the system handles them. This shows why the result displayed on the screen should not be treated as sufficient proof that the accounting treatment is correct. Compare the transaction with its original supporting document, then check its effect on the relevant accounts, reports, and balances. If differences appear, record the issue and assign responsibility for resolving it before proceeding to the next step.
To turn this concept into an actionable procedure, write a short policy covering when the step is performed, who is authorized, which documents are required, how corrections are handled, and which report management will review. When evaluating the accounting-system cycle, do not accept a general statement such as “the system supports this.” Instead, request a demonstration of a real case showing the resulting entries and documents. This makes it possible to compare solutions using practical evidence rather than promises.
How Do You Start Assessing Your Business Needs?
Start by drawing a simple map of daily operations, from creating a source document to seeing its effect in a report. Identify the number of users, branches, accounts, currencies, and data sources, then classify requirements as essential or desirable. Ideally, the accountant, operations manager, and decision-maker should all help prepare the list so that no party’s requirements are overlooked.
For each requirement, write down a real example and its expected result, then ask the software provider to demonstrate it. What matters is completing the entire process and keeping the test results for comparison.
For the accounting-system cycle in particular, it helps to turn these guidelines into a decision matrix showing each requirement, its importance, whether it is available, the test result, and the team’s notes. Avoid adopting an option whose operation cannot be explained or whose results cannot be documented. Review requirements periodically as the business grows.
To compare industry-specific applications, explore distribution solutions as a potentially relevant service page depending on your business activity, and review its functions before drawing any conclusions.
How Do You Measure Implementation Success?
You can monitor the time required to close the month, the number of unexplained differences, the proportion of corrected entries, the collection period for receivables, and the time needed to prepare reports. Do not treat indicators as ends in themselves; connect each one to a clear operational problem and a person responsible for improvement.
Establish a baseline before implementation and monitor results regularly. If invoice entry becomes faster but reconciliation errors increase, the added speed has not translated into better quality. Reviewing samples and exception reports helps identify problems early.
For the accounting-system cycle in particular, it helps to turn these guidelines into a decision matrix showing each requirement, its importance, whether it is available, the test result, and the team’s notes. Avoid adopting an option whose operation cannot be explained or whose results cannot be documented. Review requirements periodically as the business grows.
What Common Mistakes Should You Avoid?
Common mistakes include relying on marketing descriptions without testing, entering unverified opening balances, assigning overly broad permissions to speed up work, and overlooking backup or migration plans. Insufficient staff training may also lead departments to record the same type of transaction in different ways.
You can reduce these risks with a written implementation plan that specifies responsibilities, dates, test cases, and acceptance criteria. Do not activate a sensitive function until users know how to correct errors and document the reason for each change.
For the accounting-system cycle in particular, it helps to turn these guidelines into a decision matrix showing each requirement, its importance, whether it is available, the test result, and the team’s notes. Avoid adopting an option whose operation cannot be explained or whose results cannot be documented. Review requirements periodically as the business grows.
To compare industry-specific applications, explore construction management solutions as a potentially relevant service page depending on your business activity, and review its functions before drawing any conclusions.
How Do Requirements Differ by Industry?
A retail store needs fast checkout, cash reconciliation, and item integration, whereas a service company focuses on contracts, receivables, and expenses. Distribution companies add delivery and collection requirements, while contractors may need cost centers and project tracking.
Different business activities do not always require different software. A flexible system may meet several needs if the relevant functions are available and have been tested. The key is not to attribute a feature to a particular product without verifying that it actually exists.
For the accounting-system cycle in particular, it helps to turn these guidelines into a decision matrix showing each requirement, its importance, whether it is available, the test result, and the team’s notes. Avoid adopting an option whose operation cannot be explained or whose results cannot be documented. Review requirements periodically as the business grows.
What Should You Ask the Software Provider?
Ask about the limits of each plan, numbers of users and branches, data export, audit logs, backups, support hours, and the update roadmap. If your business is subject to electronic invoicing requirements, request a clear explanation of the scope of compliance instead of relying on the label “approved.”
Also ask how the system handles outages, failed synchronization, or duplicate transactions, and how service or data can be restored. Record the answers in a clear proposal or agreement, because verbal explanations can be difficult to refer back to during implementation.
For the accounting-system cycle in particular, it helps to turn these guidelines into a decision matrix showing each requirement, its importance, whether it is available, the test result, and the team’s notes. Avoid adopting an option whose operation cannot be explained or whose results cannot be documented. Review requirements periodically as the business grows.
To compare industry-specific applications, explore the purchasing management system as a potentially relevant service page depending on your business activity, and review its functions before drawing any conclusions.
How Do You Connect Educational Content to a Buying Decision?
Educational articles help explain concepts, but they do not replace an analysis of a business’s actual operations. Move from reading feature lists to preparing a short checklist, then compare it with commercial solutions that offer the required functions.
Review the relevant service page first, then request a demonstration focused on your own scenarios. If there is no documented information about a feature, price, or integration, treat it as something to verify before subscribing.
Ready to Try the System?
Start your free trial or speak with the sales team to help choose the right solution.
For the accounting-system cycle in particular, it helps to turn these guidelines into a decision matrix showing each requirement, its importance, whether it is available, the test result, and the team’s notes. Avoid adopting an option whose operation cannot be explained or whose results cannot be documented. Review requirements periodically as the business grows.
Frequently Asked Questions
What is meant by the accounting-system cycle?
It is a concept concerned with organizing accounting procedures, data, and controls in the context discussed in this article. The appropriate implementation depends on the size of the business, the nature of its transactions, and its financial system.
How can I test the electronic accounting cycle before adopting it?
Begin with a real-life scenario. Identify the source document, inputs, and expected result, then compare its effects on journal entries and reports with the approved policy.
Is the same solution suitable for small businesses and companies with multiple branches?
Not necessarily. Permissions, reporting, integration, and transaction volumes differ. The requirements of each business should be tested before making a choice.
Does having a feature in the software guarantee accurate results?
No. Accuracy depends on configuration, data quality, user training, regular review, and handling exceptions.
What is the first practical step before launching the system?
Document existing processes, identify authorized users, test sample transactions, and reconcile balances and results before launch.
Conclusion
Understanding the accounting-system cycle in practical terms helps build a reliable financial system, provided procedures are linked to source documents, permissions, reconciliations, and reports. Choosing software with an appealing name is not enough. What matters is testing the effects of real transactions, documenting responsibilities, and reviewing results continuously. Priorities differ between a small shop, a service company, and a multi-branch establishment, so the decision should begin with the business’s own needs.
Before moving to a new solution, prepare a list of essential requirements, review the commercial pages relevant to your activity, and ask the provider to demonstrate clear scenarios in front of your team. These steps turn theoretical knowledge into measurable selection criteria and can reduce the risks of errors and duplicate work during operation.
Related internal links covering financial and operational processes include accounting and point-of-sale solutions. Use the page only when it is genuinely relevant to your activity, not merely to increase the number of links.
Related internal links covering financial and operational processes include the purchasing management system. Use the page only when it is genuinely relevant to your activity, not merely to increase the number of links.
Related internal links covering financial and operational processes include distribution solutions. Use the page only when it is genuinely relevant to your activity, not merely to increase the number of links.
As a next step, you can request a practical demonstration of the required functions after defining your business needs and the functions you want to verify.
As a next step, you can visit the Nezami registration page after defining your business needs and the functions you want to verify.
Manage Your Business with Greater Flexibility
Try Digital Business for free. Start issuing electronic invoices designed to meet ZATCA requirements in minutes.