Types of Inventory Counting in Warehouses
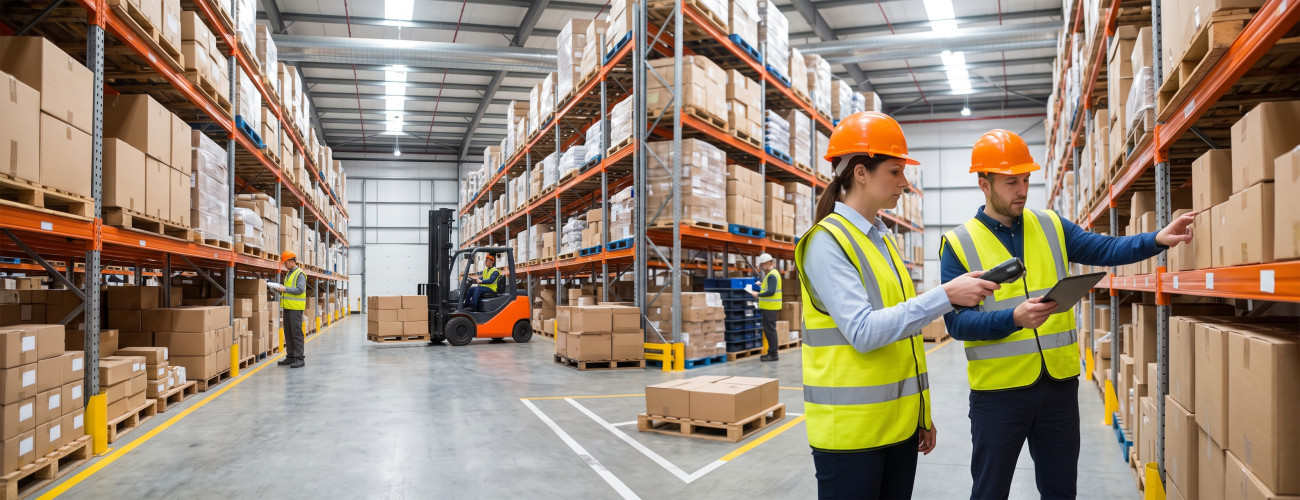
Knowing the types of inventory counting in warehouses is considered one of the basic pillars in financial management and inventory management. The presence of a recorded quantity of an item in the system does not necessarily mean that the exact quantity actually exists inside the warehouse or on the shelves.
Discrepancies may arise due to an error during receipt or issue, unrecorded returns, damage, transfers between warehouses, or incorrect quantity entry. Hence, the importance of inventory counting appears in matching the recorded balance in the system with the actual quantities present in the warehouse.
In short, the most prominent types of inventory counting include the following:
- Comprehensive Counting (Full Stocktake).
- Periodic Counting.
- Continuous or Cycle Counting.
- Partial or Selective Counting.
- Surprise Counting.
- Exceptional Counting.
No single type of inventory counting can be considered suitable for all facilities. The method is determined according to the volume of inventory, the number and value of items, the speed of their movement, the number of warehouses, and the nature of the business.
To understand inventory counting as a part of the full work cycle in the warehouse, you can benefit from the Point of Sale and Inventory Management System which helps link item movement with sales and inventory operations.
What is Inventory Counting in Warehouses?
Warehouse inventory counting is the process of verifying the actual quantities of items present inside the warehouse, then matching them with the balances recorded in the system, while identifying the causes of discrepancies and addressing them before performing the required inventory and accounting adjustments.
Example:
System recorded balance = 500 units
Actual existing quantity = 487 units
Inventory variance:
487 - 500 = -13 units
This means there is a shortage of 13 units, and its cause must be determined before adjusting the recorded balance.
Discrepancies can result from several reasons, including:
- Unrecorded sale or issue transaction.
- A returned item received without adding it to the system.
- Presence of damaged or scrapped items.
- Theft or loss in inventory.
- An error occurring upon receiving items.
- An error occurring during counting.
- Executing a transfer between two warehouses without completing the process.
- Using an incorrect unit of measurement.
- Recording an incorrect quantity in the system.
Therefore, inventory counting is not limited to counting products, but rather represents a control measure to ensure the accuracy of inventory data and the quality of recording its movement.
What are the types of inventory counting in warehouses?
Inventory methods can be divided according to the scope of items they cover, the time the operation is performed, and the reason that necessitates its execution.
| Counting Type | Execution Method | Suitable For |
|---|---|---|
| Comprehensive Counting | Counting all items | Annual closing and general auditing |
| Periodic Counting | Performed at specific times | Most companies and warehouses |
| Continuous or Cycle Counting | Repeatedly reviewing groups of items | Large warehouses |
| Partial Counting | Counting specific items | Important or high-risk products |
| Surprise Counting | Executed without announcing the scheduled time | Control and discovering discrepancies |
| Exceptional Counting | Performed due to a specific event | Changing the person in charge or the occurrence of a problem |
First: Comprehensive Counting
Comprehensive counting is a full physical count of all items located in specified warehouse locations during a specific time.
It is usually performed in the following cases:
- End of the financial year.
- Closing an important accounting period.
- Transitioning to a new accounting system.
- Rearranging or organizing warehouses.
- Conducting a comprehensive evaluation of the inventory.
- Auditing works.
Advantages of Comprehensive Counting
- Provides a complete picture of the actual balance.
- Helps discover discrepancies in a large number of items.
- Supports reviewing inventory value.
- Provides an appropriate basis for making adjustments.
Disadvantages
Executing a comprehensive count may require:
- A long period of time.
- A large number of employees.
- Advance preparation and organization.
- Suspending or limiting some movements during the counting process.
- Careful review of the counted items.
Therefore, applying it frequently may become impractical for facilities that manage thousands of items.
Second: Periodic Counting
Periodic counting means executing the counting process in predefined time periods, such as the end of the month, financial quarter, half-year, or year.
Examples include:
- Monthly count.
- Quarterly count.
- Semi-annual count.
- Annual count.
The facility determines the frequency of counting according to the business volume and the level of risks associated with the inventory.
When is Periodic Counting suitable?
This method is suitable when:
- Item volume is medium.
- The facility does not require daily inventory counting.
- Inventory movement can be controlled.
- Specific schedules exist for review.
The facility can organize counting cycles according to its operational needs, utilizing the Purchasing Management System in organizing part of the purchasing and receiving movements linked to inventory.
Third: Continuous or Cycle Counting
Continuous counting or Cycle Counting relies on reviewing specific groups of items repeatedly during the year, instead of waiting for a single time to count the entire inventory.
For example, items can be distributed into groups as follows:
- Group A: once a week.
- Group B: once a month.
- Group C: once a quarter.
Items with a higher value or faster movement are usually given a higher frequency of counting.
Why do companies use Continuous Counting?
This method helps to:
- Detect errors early.
- Limit the accumulation of inventory discrepancies.
- Avoid waiting until the end of the year to discover problems.
- Direct counting toward the most important products.
- Raise the level of accuracy of data in the system.
- Reduce the need to halt business activities for long periods.
This method is particularly suitable for large stores, distribution companies, and warehouses containing large numbers of items.
Does Continuous Counting mean there is no need for a physical count?
No.
A common mistake is confusing continuous recording of inventory movement with actual physical counting of items.
The system can update balances when executing purchase, sale, issue, and transfer operations, but physical counting remains important to ensure that the recorded balance matches the quantity existing in reality.
Also, the Point of Sale and Item Management System helps in tracking the movement of products and inventory within the operations ecosystem, while the accuracy of balances remains linked to the correct recording of operations and execution of physical counting.
Fourth: Partial or Selective Counting
Partial counting means counting a specific group of items without performing a full count of all inventory.
Items can be chosen according to several criteria, such as:
- High value of the item.
- Fast movement of the product.
- Recurrence of previous discrepancies.
- Its susceptibility to damage or loss.
- Approaching expiration date.
- Importance of the item to the business.
Example
Suppose a store has 5,000 items, and management discovers that 150 of them represent a large percentage of the inventory value.
Instead of executing a weekly count for all 5,000 items, the frequency of counting the 150 higher-importance items can be increased.
This method is also known in some environments as selective counting.
This method can be supported by using a Distribution and Inventory Management System when the movement of items between locations and branches is a core part of the business.
Fifth: Surprise Counting
Surprise counting is conducting a counting process without notifying the employees in charge of the inventory in advance.
This type is usually used for control purposes and verifying the accuracy of balances and procedures.
Management may decide, for instance, to perform a surprise count on:
- The cash register and inventory.
- A high-value item.
- A specific warehouse.
- A branch where discrepancies frequently appeared.
- Fast-moving items.
What is the goal of Surprise Counting?
Surprise counting helps in:
- Detecting unusual discrepancies.
- Measuring the level of compliance with work procedures inside the warehouse.
- Limiting the possibilities of manipulation.
- Ensuring the correct recording of receipt and issue operations.
- Testing the effectiveness of internal control.
It is not supposed to replace the main counting plan, but rather is used as an additional control tool.
Sixth: Exceptional Counting
Exceptional counting is performed when a specific event occurs that necessitates urgently verifying the actual inventory balance.
Cases that might necessitate this include:
- Changing the warehouse keeper.
- Handing over the warehouse to a new person in charge.
- Discovering a massive discrepancy in the balance.
- Occurrence of theft.
- Outbreak of a fire or occurrence of damage.
- Relocating the warehouse.
- Merging two branches.
- Changing the inventory management system.
- Liquidating the business.
The goal of this type is not to adhere to a specific periodic schedule, but rather to establish the true balance at a certain date and determine the responsibility associated with it.
What is the difference between Periodic and Continuous Counting?
The difference between periodic counting and continuous counting is considered one of the most raised topics when studying the types of inventory counting in warehouses.
| Comparison | Periodic Counting | Continuous Counting |
|---|---|---|
| Timing of count | Within specific schedules | Repeatedly during the year |
| Items | A large number or full inventory | Specific groups |
| Discovering errors | When the scheduled counting time arrives | Usually much sooner |
| Halting operations | Might be higher | Is usually lower |
| Number of items | Suitable for less complex inventory | Suitable for large inventory |
| Tracking | Done in intervals | Done continuously |
| Planning | Specific schedule for counting | Cycle counting program throughout the year |
In practical application, both methods can be combined within the same facility.
The facility might adopt a comprehensive periodic count once annually, alongside applying continuous counting for important items during the rest of the year.
The Difference between Comprehensive and Partial Counting
Comprehensive counting includes all existing items, while partial counting is limited to a specific group of them.
Example:
If the warehouse contains 10,000 items:
- Counting 10,000 items = Comprehensive counting.
- Counting only 500 items = Partial counting.
Partial counting is characterized by rapid execution, but on its own, it does not provide a complete picture of all warehouse balances.
Which type of counting suits your business?
The appropriate counting method differs according to the nature of the business and the inventory volume:
| Business | The Generally Suitable Method |
|---|---|
| Small shop | Periodic + Surprise when needed |
| Supermarket | Continuous + Periodic |
| Distribution company | Continuous + Selective + Comprehensive |
| Large warehouse | Cycle Counting + Comprehensive |
| Restaurant | Continuous for important materials + Periodic |
| E-commerce store | Continuous + Selective |
| Factory | Continuous for important materials + Periodic Comprehensive |
| High-value items | Selective and Surprise at a higher frequency |
Ready to try the system?
Start your free trial or talk to the sales team to help you choose the right solution.
It is not necessary to strictly adhere to this classification individually, as the facility might need to combine more than one method depending on the level of risk and the nature of the inventory.
Also read: A simplified guide explaining distribution management and item movement
How is inventory counting done in warehouses step by step?
An organized counting process begins with advance preparation, not just when the actual counting starts.
1. Defining the inventory scope
You must determine:
- The target warehouse.
- The items included in the count.
- Storage locations.
- Date of execution.
- The people in charge.
2. Organizing inventory movement
You should control the operations of:
- Receipt.
- Issue.
- Transfer.
- Returns.
So that an item is not counted at the exact time it is being moved without recording it.
3. Extracting the recorded balance
Balance data is prepared from the system so it can be compared with the quantities that appear during the physical count.
4. Physical counting
The existing quantities in the storage locations are counted, and the results are recorded accurately.
It is preferable to distinguish between:
- Intact quantities.
- Damaged items.
- Expired products.
- Reserved products if the business procedures require so.
5. Comparing actual with system
The difference can be calculated using the following formula:
Inventory Variance = Actual Quantity - Recorded Quantity
If the result is negative → Shortage
If the result is positive → Surplus
6. Investigating discrepancies
Adjustment should not be executed immediately once the difference appears.
Instead, you should review:
- Latest sale operations.
- Purchases.
- Transfers.
- Returns.
- Damaged items.
- Units of measurement.
- Data entry errors.
7. Recounting items with discrepancies
Especially the items that are characterized as being:
- High value.
- Having huge discrepancies.
- Sensitive.
- Fast-moving.
8. Approving the adjustment
After verifying the cause of the discrepancy and having the action approved by the authorized person, the balance is adjusted according to the adopted inventory and accounting policies and procedures of the facility.
The Point of Sale System helps in tracking the movement of products, inventory, warehouses, and suppliers within the operations ecosystem, supporting tracking the source of the discrepancy instead of just looking at the final balance.
What is an inventory report?
An inventory report is the document that displays the results of the counting process and clarifies the discrepancies between the balance present in the system and the actual quantity.
It is preferable that it contains:
| Description | Example |
|---|---|
| Item Code | A-100 |
| Item Name | Product A |
| Warehouse | Main |
| System Balance | 100 |
| Actual Balance | 96 |
| Difference | -4 |
| Unit Cost | 50 SAR |
| Variance Value | -200 SAR |
| Reason | Under Review |
| Action | Recount / Adjustment |
Ready to try the system?
Start your free trial or talk to the sales team to help you choose the right solution.
With repeated counting operations, items that repeatedly have discrepancies can be analyzed instead of dealing with every counting result individually.
What are the causes of inventory discrepancies?
The appearance of a discrepancy in counting does not necessarily mean there is a theft or loss in inventory.
The most prominent potential causes include:
Receiving Errors
Such as recording the receipt of 100 units while the actually received quantity is 98 units.
Issuing Without Recording
A quantity exiting the warehouse without recording the transaction in the system.
Unit of Measurement Errors
Such as failing to properly distinguish between:
- Piece.
- Carton.
- Pack.
Returns
Physically returning the product to the warehouse without updating its balance in the system.
Damage and Scrap
Removing a product from usage without recording the damage or scrap transaction.
Transfer Between Warehouses
Deducting the quantity from the first warehouse without completing the receiving operation in the other warehouse.
Counting Errors
Which appear particularly in small items or in warehouses that lack organization.
Barcode or Item Identification Errors
Some products might be similar or codes might be duplicated, leading to recording the movement on a different item.
How do you reduce inventory discrepancies?
Inventory counting helps discover the problem, but alone it is not enough to prevent its recurrence.
To reduce discrepancies, you can follow the following:
- Record every movement as soon as it is executed.
- Utilize barcodes when they suit the nature of the business.
- Distribute receipt, issue, and review permissions.
- Arrange and organize storage locations.
- Record damaged items at the time they occur.
- Review transfer operations between warehouses.
- Execute continuous counting for important items.
- Track return operations.
- Analyze items that repeatedly show discrepancies.
- Link inventory with sales and purchasing operations.
The Purchasing Management System helps to organize part of the purchasing and receiving cycle, while linking operations contributes to improving inventory tracking before reaching the adjustment phase.
Manual counting or counting using software?
Counting can be executed manually in warehouses with limited size, but managing the process becomes more complex as the number of items and branches increases.
Manual Counting
Can rely on:
- Counting forms and papers.
- Excel.
- Entering results manually.
This suits small and limited operations; however, the probability of errors rises as the data volume increases.
Counting Using an Inventory Management System
The system helps in:
- Extracting the recorded balance.
- Managing more than one warehouse.
- Tracking the movement of each item.
- Proving adjustments.
- Identifying low-quantity products.
- Analyzing inventory discrepancies.
- Linking inventory to sales and purchases.
The Point of Sale System can support tracking items, quantities, costs, warehouses, and product movement, alongside sales, suppliers, and financial and accounting reports.
As for facilities relying on cloud operations, they can use the Cloud System and register for the trial period to manage inventory, purchases, and item movement within a cloud operating environment.
How does counting affect accounts?
The importance of counting is not limited to the inventory aspect, as the actual balance of the inventory is linked to financial reports, cost of sales, and profitability.
If the recorded balance in the system is greater than the actually existing quantity, it may lead to displaying an inaccurate value of the inventory within reports.
Therefore, the following operations should be linked:
Purchases → Receipt → Inventory → Sales → Cost of Sales → Counting → Adjustment → Reports
Within an interconnected work cycle.
You can book your consultation with our team to learn about the right solutions for your business, or register and start the trial period to fully experience the system.
Common mistakes during counting
Among the most prominent mistakes that might happen during the counting process:
- Counting items while issue operations continue without any control over them.
- Executing an adjustment before determining the cause of the discrepancy.
- Not recounting items that show massive discrepancies.
- Placing damaged items with intact products.
- Neglecting differences in units of measurement.
- Not recording the person responsible for executing the count.
- Assigning both the counting and approval process to the same person without review.
- Not repeating the counting for high-value items.
- Relying only on the annual count in high-movement warehouses.
- Not studying the causes of discrepancies after the counting process is finished.
Frequently asked questions about types of inventory counting in warehouses
What are the types of inventory counting in warehouses?
The main types include comprehensive counting, periodic counting, continuous or cycle counting, partial or selective counting, surprise counting, and exceptional counting.
What is Periodic Counting?
It is performing an inventory count on specific dates, such as the end of the month, quarter, or year, then comparing the actual quantities to the recorded balances.
What is Continuous Counting?
It is repeatedly reviewing specific groups of items throughout the year, in parallel with the system updating sales, purchases, issues, and transfer movements.
What is the difference between Periodic and Continuous Counting?
Periodic counting takes place at specific times, while continuous counting relies on reviewing groups of items repeatedly throughout the year, which helps discover discrepancies early on.
What is Surprise Counting?
It is executing a counting process without a prior announcement of its date, aimed at control and verifying that the actual balance matches.
What is Partial Counting?
It is counting a selected group of items instead of performing a full inventory count, such as high-value or fast-moving products.
Does Continuous Counting cancel out the Annual Count?
Not necessarily, as the facility can execute continuous counting throughout the year alongside a comprehensive count on a specified date in accordance with its policies and audit requirements.
What should I do when there is a discrepancy in the count?
Start by recounting the item, then review sales, purchases, returns, transfers, damaged goods, and units of measurement before approving any adjustment.
Does inventory software prevent counting discrepancies?
Software does not completely prevent discrepancies, but it helps in recording and tracking movements and reaching the source of the difference much faster. Proper procedures, control, and physical counting remain essential elements.
Conclusion
Understanding the types of inventory counting in warehouses helps a facility choose the appropriate control method instead of relying on one single annual count for all cases.
Comprehensive counting provides a complete picture, while periodic counting organizes the review process on specific dates, continuous counting helps detect errors early, partial counting focuses on important items, and surprise counting serves as an additional means for control.
In many facilities, more than one method can be combined, such as applying continuous counting for high-value items, along with periodic counting for the rest of the inventory, and executing a comprehensive count at the end of the period.
Since counting accuracy starts before the actual counting process itself, it is necessary to record purchases, sales, transfers, returns, and damages within an interconnected ecosystem. You can utilize the Point of Sale System to link inventory movement with sales, purchases, suppliers, warehouses, and reports, with the ability to book a consultation to learn about the solution appropriate for the nature of the business.
Start managing your business with complete flexibility
Try Aamal Raqamiya (AamalSoft) for free. Start issuing your ZATCA-compliant electronic invoices in minutes.