Artificial Intelligence in Accounting: How Can You Streamline Invoice Entry with a Cloud Accounting System?
📅 19/11/2026
Artificial intelligence in accounting helps extract data from documents, suggest transaction classifications, and detect certain unusual cases. Its practical value, however, emerges when these suggestions become data that an accountant reviews before approval. When using a cloud accounting system to receive purchase invoices, you can design a workflow that reduces manual typing without sacrificing the accountant’s control over the accuracy of entries, tax, and inventory.
Imagine a store receiving dozens of supplier invoices every week in different formats: smartphone photos, PDF files, and structured electronic documents. Some invoices are lengthy, while others contain discounts and similar-looking items. If an employee transfers the figures manually, they may duplicate an invoice or select the wrong unit of measure. If they rely on automated reading without review, however, the same mistakes may simply happen faster. The aim of this guide is to build a measurable automation workflow, not to replace the accountant with a text-generation tool.
What Are the Uses of Artificial Intelligence in Everyday Accounting?
The most practical applications begin with reading documents and converting them into structured fields. A solution that supports optical character recognition or document-understanding models can suggest the invoice number, date, supplier name, line items, and amounts. Some solutions can also suggest the appropriate account or detect similarities between a new document and an earlier one. Capabilities vary by product, language, and image quality, so do not assume that all tools provide these functions.
There is a difference between extracting data and interpreting it. Reading the number 1,150 from an image is an extraction task; determining whether that amount represents a fixed asset, an expense, or inventory is an accounting decision that depends on the nature of the purchase and the business’s policy. Likewise, the appearance of tax on an image does not prove that the business can deduct it. The accountant must review the eligibility requirements and supporting documents under the VAT Implementing Regulations.
| Task | What automation can suggest | What the accountant reviews |
|---|---|---|
| Invoice reading | Number, date, and amount | Match to the original |
| Supplier classification | Name or number match | Identity and account |
| Item classification | Suggested internal code | Unit and quantity |
| Tax | Extract rate and amount | Treatment and deductibility |
| Duplicate detection | Similar document | Is it actually a duplicate? |
How Does AI-Powered Invoice Reading Work?
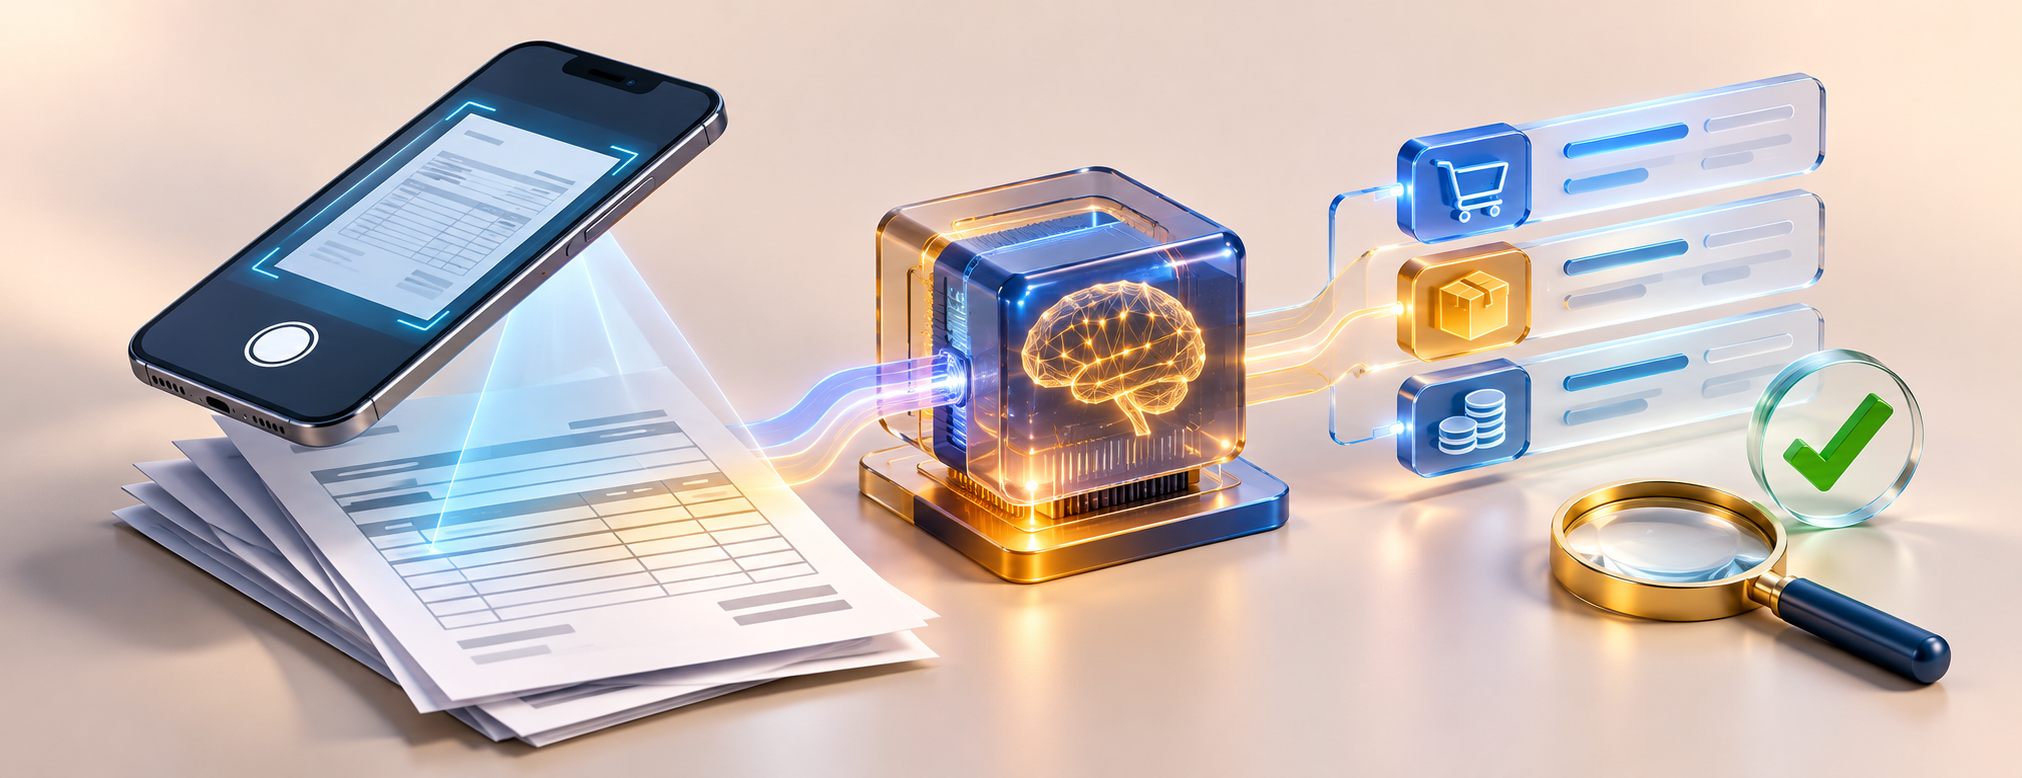
A document typically passes through intake, processing, extraction, and validation stages. At intake, the employee uploads the file from a known source. The system may correct the image orientation or remove noise. It then extracts the fields and displays them in a draft. Validation rules are subsequently applied, such as checking that the line items, tax, and total reconcile. The draft should not become an approved purchase invoice until the specified controls have been completed.
If a structured electronic file containing the original data arrives, it is usually preferable to use the structured fields rather than reread the image. Visual recognition may confuse 0 with 8, or a date with a reference number. The source and accuracy of the data must still be verified. If the invoice is a low-resolution image, request a clearer copy rather than guessing. Review the procurement cycle to determine where the draft fits into purchasing, receiving, and approval procedures.
Book a demo and ask about entering purchases from files.
Preparing Supplier Data Before Automating Accounting
The quality of the supplier database matters more than the quality of the model alone. If the same supplier is registered under three names, the tool may suggest the wrong account or create a new record for every invoice. Assign a stable internal identifier to each supplier and link it to verified tax information. Do not rely on name similarity alone, particularly when trade names are similar or a group has several legal entities.
Establish a policy for new data. When the system does not recognize a supplier, the invoice should remain in the review queue until an authorized employee approves the creation of a record. When a new bank account number appears on an invoice, do not change payment details automatically; verify them with the supplier through a known, independent channel. An invoice may look correct while containing fraudulent payment instructions.
In a hypothetical example, a document arrives in the name of Al Noor Trading Establishment, while the database contains Al Noor Supplies. The tax number is different. A high similarity score is not enough to assign the invoice to the existing account. Compare the contractual documents, tax number, and supplying entity. Customer and supplier account statements help reveal the impact of selecting the wrong account after posting.
Matching Items and Units of Measure
If a business purchases 12 cartons, each containing 24 units, the inventory quantity in individual pieces is 288. If the tool reads only 12 and associates that number with the piece unit, the recorded quantity will be far below the actual quantity. If a carton costs SAR 120, the cost per piece before tax is SAR 5, not SAR 120. These errors may not appear in the invoice total, but they affect the cost of sales and stocktaking.
Create a conversion table for approved units and link the supplier’s item code to the internal item code whenever possible. Do not allow a new item to be created merely because the packaging description differs. When the pack size changes from 24 to 20 units, review the conversion factor and its effective date. Match the reading results to the purchase order and goods receipt. If the quantity received is lower than the invoiced quantity, do not approve the full inventory entry until the reason for the difference has been determined.
Warehouse management and stocktaking illustrate the importance of units and balances. When testing automation, select a document containing a different unit of measure, a line-level discount, and an overall discount. Verify the quantity and cost, not just the total amount.

Accounting Example: From a Purchase Invoice Image to a Journal Entry
Suppose a store receives 10 units of an item priced at SAR 100 per unit, with a SAR 100 discount before tax. The net value is SAR 900, VAT at 15% is SAR 135, and the total is SAR 1,035. Assume that the business is VAT-registered, the tax is deductible, and the items are merchandise inventory. For a credit purchase, the entry is a debit to inventory of SAR 900, a debit to input VAT of SAR 135, and a credit to accounts payable of SAR 1,035.
| Field | Expected value | Review test |
|---|---|---|
| Quantity | 10 | Match the receipt |
| Value before discount | 1,000 | 10 × 100 |
| Discount | 100 | Match the document |
| Tax | 135 | 900 × 15% |
| Total | 1,035 | 900 + 135 |
If the tool suggests tax of SAR 150 because it reads the amount before the discount, the difference is SAR 15. Validation should prevent the draft from being approved until the accountant reviews how the discount was allocated. If the supplier has issued a document with different amounts, do not correct the invoice image yourself; request the correct document or follow the appropriate procedure with the supplier.
After approving the draft, compare the inventory, payable, and tax entries with the original document. If the invoice is paid immediately, the credited account differs according to the payment method. Review input VAT reconciliation to understand the subsequent review of the tax return.
Try the system with a test invoice before applying it to your actual purchases.
Preventing Duplicate Purchase Invoices During Automation
An invoice may arrive by email, then be uploaded by a warehouse employee, and later be imported again by the accountant. The filename alone is not enough to detect duplication; the name or document format may change. Combine the supplier number, invoice number, date, value, and source identifier in a validation database. Use the file fingerprint as an additional signal, but do not rely on it alone because two copies of an invoice may differ in resolution or page order.
Some similarities are legitimate. Two different suppliers may issue invoice number 100, and a supplier may issue a credit note with a similar number. Do not delete a document automatically merely because the amount is similar. Show the reviewer the candidate matches and the reason for suspicion. You can also consult handling duplicate supplier invoices to design a policy that prevents double payments.
If an invoice has been approved and a clearer file subsequently arrives, attach the file to the existing record instead of creating a new purchase transaction. If the invoice has been corrected by a later document, preserve the relationship between the two documents. Do not replace the original with a modified file that loses the audit trail.
Confidence Limits and Human Review in AI-Powered Accounting
The tool may display a high confidence score for a field extraction, but that is not evidence that the accounting treatment is correct. Rules can make the supplier number, invoice total, or tax sensitive fields that require explicit verification. The system may allow low-risk drafts to proceed after a brief review, while large or unusual invoices require a second approval.
Define a test sample before implementation. Take, for example, 100 varied invoices, then compare each field with the correct result. If the tool reads 95 invoice numbers correctly, the accuracy of that field is 95% in that sample only; it is not the accuracy of all invoices or a guarantee of future performance. If total accuracy is 99% and unit-of-measure accuracy is 80%, focus improvements on units. Record errors by supplier and document type, and repeat the test whenever the model or its settings change.
Do not ask a language model to invent a missing value or reconstruct a tax number that is not visible. Treat a missing value as an explicit exception. If the document is unreadable, the correct action is to request another copy. Review internal accounting controls to determine approval levels.
Protecting Business Data When Using AI Tools
Purchase invoices sometimes contain names, addresses, contact information, and contractual prices. Before uploading them to any external service, review the business’s policy and its contract with the provider, where data is processed, who can access it, whether it is used to train models, and how it is deleted or retained. Do not upload customer and supplier documents to unapproved personal tools simply because they are faster to use.
Assign permissions for uploading, reviewing, and approving documents. The employee receiving an image does not necessarily need to modify accounts or supplier bank details. If the solution allows fields that are unnecessary for processing to be masked, use that feature in accordance with the business’s policy. Ask the provider to explain its audit trail and document retention mechanisms, and verify the data protection obligations applicable to your business activity.
Explore the plans and ask about file-processing limits and permissions.
Measuring the Return on Invoice Entry Automation
Do not measure project success by the number of images the system has read. Measure the total time from document arrival to entry approval, the error rate, and the amount of rework. Consider a hypothetical example: 600 invoices per month, each taking four minutes to enter manually, for a total of 40 hours. If average reading and review time falls to two minutes, the total becomes 20 hours. At a time cost of SAR 60 per hour, the theoretical savings are SAR 1,200 per month before the cost of the tool, training, and error correction.
| Metric | Before automation | After automation in the example |
|---|---|---|
| Number of invoices | 600 | 600 |
| Average processing time | 4 minutes | 2 minutes |
| Total time | 40 hours | 20 hours |
| Value of time | SAR 2,400 | SAR 1,200 |
If the service costs SAR 700 per month, the theoretical savings remaining are SAR 500 before other expenses. The return may be greater if payment errors decrease or closing becomes faster, but this is not guaranteed. Do not count time that the system shifts from data entry to error correction as time saved. Use accounting system reports to monitor approved and pending invoices, and set a measurable target for each month.

A Four-Week Trial Plan
In week one, identify document sources, document types, and the required databases. In week two, test a representative sample and compare the fields with the originals. In week three, run the workflow with a limited group of suppliers and conduct a full review. In week four, compare the results and determine whether expansion is appropriate. Do not start with the most complex suppliers, and do not rely only on simple invoices.
Choose test cases that include a multipage document, an unclear image, a discount, a return, a carton unit, a new supplier, and a duplicate document. Document the cause of each failure and determine whether it requires a settings correction, a technical improvement, or training. When expanding, maintain a queue of incomplete documents so that invoices are not lost if automated reading fails.
Discuss the procurement scenario suited to your business with the Digital Plus team.
Practical Cases and Advanced Reviews
How Do You Design Validation Rules Before Approving an Invoice?
You can begin with five independent rules: matching the line-item total, matching the tax to the applicable category, identifying a known supplier, ensuring that the document number is not duplicated for that supplier, and matching the quantity to the receipt. Do not make every rule trigger the same action. A total discrepancy may prevent approval, while a difference in item description may merely trigger a review request. Define rules according to the impact of an error on accounts, inventory, and tax.
For an invoice with 50 line items, the model may read 49 correctly and make an error on one. If the missing line is worth SAR 2,000, the line-level reading success rate does not reflect the financial risk. Monitor the accuracy of material amounts rather than relying solely on the percentage of correct fields. An additional review threshold may be set for invoices exceeding an amount that the business determines according to its own risks, rather than a universal figure imposed on every company.
| Validation rule | Condition requiring a stop |
|---|---|
| Total | Line items plus tax do not equal the final amount |
| Supplier identity | Tax number differs from the approved record |
| Quantity | Invoiced quantity exceeds the receipt without explanation |
| Duplication | An invoice with the same reference exists for the supplier |
| Classification | An unapproved item or account requires a decision |
Handling Service and Asset Invoices, Not Just Inventory
A restaurant may purchase a new refrigeration unit, cleaning supplies, and a maintenance service on one document. Do not classify all lines as inventory merely because the document comes from a familiar supplier. The equipment may be a fixed asset if recognition criteria are met, cleaning supplies may be an expense or supplies inventory depending on policy, and maintenance may be an expense or part of an asset’s cost depending on its nature. The review workflow must support allocating line items to the appropriate accounts and cost centers.
If the equipment invoice amounts to SAR 20,000 before tax and the maintenance costs SAR 1,500, do not use the account the model selected for an earlier invoice from the same supplier without checking. Review the purchase order, goods receipt, and capitalization policy. Part of the document may relate to a branch and another part to the head office. When testing automation, include a case with more than one cost type and verify that the system allows the suggested classification to be changed before approval while preserving the review trail.
What Happens When an Invoice Arrives Before the Goods Are Received?
A supplier document may arrive by email before the shipment arrives. If the business uses purchase orders and goods receipts, determine whether the invoice will remain pending until matching is complete or will be processed according to the policy for goods in transit and liabilities. Do not allow automated reading to increase inventory available for sale merely because a document has arrived. The point at which inventory and the liability are recognized depends on the purchase terms and the transfer of control.
Suppose the supplier invoices 100 units, but the warehouse receives 95. The five units may be in another shipment, missing, or rejected. Do not change the original invoice quantity to match the receipt; retain the document and request an explanation for the difference. If the system supports three-way matching, test the relationship between the purchase order, receipt, and invoice. If it does not, use a documented checklist before approving the entry.
Measuring the Impact of Automation on Closing Quality
A common mistake is to regard the number of invoices approved each day as a sufficient indicator. That number may rise because an employee bypassed review, only for the accountant to spend days correcting accounts at month-end. Compare the number of entries that needed adjustment, the number of unallocated invoices, inventory discrepancies, and documents that did not reach the reviewer. Also monitor the waiting time between invoice arrival and approval, not just the time required to read the image.
If the business processes 600 invoices monthly and average entry time decreases by two minutes, but 30 invoices require corrections taking 10 minutes each, five hours of rework must be deducted from the theoretical savings. If the initial savings are 20 hours, net time saved becomes 15 hours before accounting for training and follow-up. This example helps management make a decision based on overall performance, not on how quickly fields appear in a demo.
Procedures for Changes in a Supplier’s Invoice Layout
A supplier may change the invoice layout or add a new discount table. Keep a sample of the new format and test it before allowing expedited approval. If an error recurs for one supplier, do not disable automation for all suppliers; instead, increase the level of review for that supplier until the cause is resolved. If the error relates to a document type such as a credit note, establish a separate workflow for that type.
Record the tool version or the date of a settings change whenever possible, then compare results before and after the change. Ask the provider to explain how it handles multipage documents, Arabic, and dates. Do not use real data to train or test an external service before verifying permissions and data protection terms. This way, the process improves gradually while the accountant remains responsible for approving the records.
Reviewing Outputs Before Approving Expansion
Compile the test results in a report showing which document types succeeded, which fields required review, how much time was spent, and which cases should be excluded from the automated workflow. If one supplier sends invoices in an unstructured format, requesting a structured electronic file may be preferable to spending more time correcting the extraction. If errors recur because of internal item data, improving the database may be more useful than changing the tool. Also compare the impact of automation on the accounting workflow, because faster data entry creates no value if approval is delayed or the original document is lost. Approve expansion only when the sample results can be explained and employees know when to stop approval and request review.
Ready to Try the System?
Start your free trial or speak with the sales team to help choose the right solution.
Frequently Asked Questions
Can Artificial Intelligence Approve Invoices Without an Accountant?
Some procedures can be automated under appropriate controls, but accounting and tax decisions should not rely on an unverified suggestion. The business determines the level of review appropriate to its risks.
Does Reading an Invoice from an Image Make It a Compliant Electronic Invoice?
No. Automated reading is a data-entry method, not the issuance of an electronic invoice that complies with the authority’s requirements.
Can Arabic Invoices Be Extracted?
That depends on the solution and document quality. Test Arabic, numbers, dates, and units on a realistic sample.
What If the Total Is Correct but the Line Items Are Wrong?
Review the line items, quantities, and costs. The total may match while inventory or expense classification is distorted.
Can Artificial Intelligence Be Used to Detect Duplicates?
Yes, as an assistive tool, with clear matching rules and a review of legitimate similarities.
How Do I Know Whether the Tool Saves Time?
Compare total processing time and the rework rate before and after implementation, rather than relying on extraction time alone.
Conclusion
Artificial intelligence in accounting is useful when it streamlines document entry and makes exceptions more visible without weakening controls. Start with clean supplier and item data, reviewable drafts, validation rules, and periodic measurement of results. The comprehensive guide to cloud accounting software helps explain where this function fits within the system, and you can explore accounting and point-of-sale solutions when assessing integration with other operations.
Start a practical trial and identify the supported functions before subscribing.
Manage Your Business with Greater Flexibility
Try Digital Business for free. Start issuing electronic invoices designed to meet ZATCA requirements in minutes.